Enter your address and we’ll send you every hail and wind event on record for it — the dates, the hail sizes, the wind speeds, and whether any of it is worth a closer look. No visit, no obligation, and you decide what happens next.

Not fine print. These apply to every job we take.
Whether it’s a house in Fort Worth or a building with tenants in it, the process is the same — document it properly, get it approved properly, build it back properly.

Storm damage, insurance claims, full replacements and repairs — with the free impact-resistant upgrade and a 5-year workmanship warranty on every roof.

Low-slope and steep-slope commercial systems, phased so the building keeps operating. Documentation your carrier and your property manager can both work from.
If it’s a roof in DFW, we inspect it, we document it and we build it back. Residential and commercial, steep-slope and low-slope.
Not sure what you’ve got up there? We’ll tell you — free, and without anyone coming to your address.
Most homeowners have no idea whether their roof was hit. Here are two ways to find out. Both are free, and neither one obligates you to file a claim or hire anybody.

We pull the verified hail and wind history for your exact address and email it to you.

We fly your roof with a drone and run the imagery through ScanShield AI damage detection, then hand you the report.
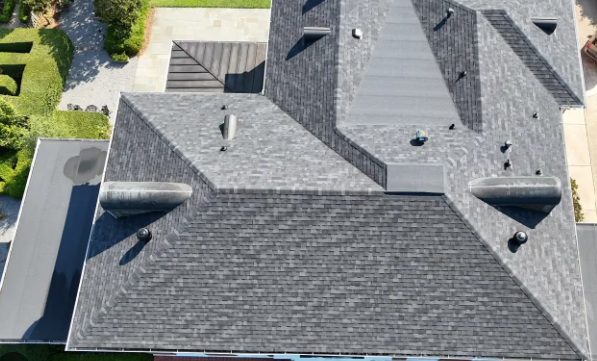
Hail bruising doesn’t look like damage from the ground. We fly the roof at high resolution and let ScanShield AI mark every hit, so what’s on your report is what’s actually on your roof.
Illustration of how a scan report marks damage. Your report shows the actual detections from your own roof.
The drone comes first because it costs you nothing and nobody has to come to your address. Once there’s a reason to look closer, we’re on the roof — hands on the shingles, at the inspection, next to your adjuster, and every day of the tear-off and install. What we don’t do is put unnecessary foot traffic on damaged material before the damage has been documented.
High-resolution imagery of every slope, run through ScanShield AI. You get a written report with photos — free, no appointment, nobody at your door.
If the imagery shows something, we come out and get on the roof. Hands-on test squares, lifted tabs, flashing, decking, ventilation — the things you can only judge up close.
We meet your adjuster on site and walk the roof with them, so what goes in the scope is what’s actually up there — not what got missed from the driveway.
Tile, slate and metal get extra care — those crack, dent and oil-can under a careless footstep, and once that happens nobody can tell the storm’s damage from somebody’s boots. We document from the air first, then walk them on the right paths. Same roof, same crew, better claim.
RezComm inspects roofs on residential and commercial properties across DFW — asphalt shingle, standing-seam and exposed-fastener metal, clay and concrete tile, slate, TPO, PVC, EPDM, modified bitumen, built-up and gravel-surfaced roofs, coatings, and other low-slope and specialty systems.
Depending on the property and the roof type, an inspection may include any of these.
You get a free, plain-English inspection report with photographs, documented findings, an explanation of any damage or potential problems, and recommended next steps. Whether it’s a leak, recent hail or wind, normal aging, property maintenance, or a roof you need checked before buying or selling — you get an honest assessment either way.
Most claims get written off one walk-around by somebody who has four more stops that day. We meet your adjuster at the property with the ScanShield AI scan, photographs of every slope, and a line-by-line estimate of what the repair actually takes — so the scope on paper matches the roof.
It has to come from you — you’re the policyholder. We’ll tell you exactly what information your carrier will ask for so the call takes five minutes instead of thirty.
Usually within a week or two. Tell us the date and time as soon as you have it.
We bring the drone imagery, the ScanShield AI detections, slope-by-slope photos, and our measurements. Nothing about your roof gets decided without documentation in front of it.
It lists the approved scope and the first payment — the actual cash value, less your deductible. We’ll walk you through what each line on it means.
If the estimate leaves out something the repair genuinely requires — decking, flashing, ventilation, code-required items — we photograph it, document it, and submit it to your carrier as a supplement to our estimate. Supplements are a normal part of a roof claim, not a fight.
Permitted, installed to the manufacturer’s specification, cleaned up the same day. Most DFW homes are a one-day tear-off and install.
Once the work is complete we send your carrier the completion documentation it requires, and it releases the recoverable depreciation it held back. You pay your deductible — that part is yours by law — and you’re done.
Completion certificate, impact-resistant shingle certification for your discount, warranty, permit — we prepare all of it and walk it through with you.
RezComm is a roofing contractor, not a public insurance adjuster. Under Texas law a roofing contractor may not act as a public adjuster on a property it is contracted to repair (Tex. Ins. Code § 4102.163). So we don’t negotiate your claim, interpret your policy, or tell you what your carrier owes you — every decision on the claim stays yours. What we do is document the damage accurately and estimate the repair honestly, and in our experience that is what actually moves a scope.
Texas law also requires the insured to pay any deductible applicable to a claim. We cannot and will not waive, absorb, rebate, or fail to collect your deductible.
On qualifying insurance-funded roof replacements we upgrade you to impact-resistant shingles at no additional charge. You pick the class and the brand — we’ll show you the options and what each one does.
You come out of the claim with a brand-new roof built to a higher standard than the one that got hit — new decking where it’s needed, code-compliant ventilation, and a full manufacturer warranty on the material.
Most Texas carriers offer a discount for an impact-resistant roof. We hand you the signed certification your carrier needs to apply it — and that discount keeps coming back every year you own the house.
Impact-resistant shingles are tested against hail that cracks and bruises a standard shingle. The next storm that would have put you through this whole process again may not leave a mark.
No claim, no adjuster, no deductible, no crew in your driveway — because there was nothing to file. That’s the part most people don’t think about until the second hailstorm.
A recent roof with a transferable manufacturer warranty and an impact-resistance rating is one of the first things a buyer’s inspector writes down — and one of the last things they argue about.
We’ll lay out the classes and the manufacturers, tell you honestly what the difference is worth on your roof, and install whichever one you choose.
Impact-resistant shingles reduce hail damage; they are not damage-proof, and no roof is. Carrier premium discounts are set by your insurer, not by RezComm, and are not guaranteed.
Full roof replacement on insurance claims — documented, permitted, and warrantied.
Architectural and impact-resistant shingles from every major manufacturer, in the class you choose.
Standing seam and exposed-fastener panel systems for homes that want the last roof they’ll ever buy.
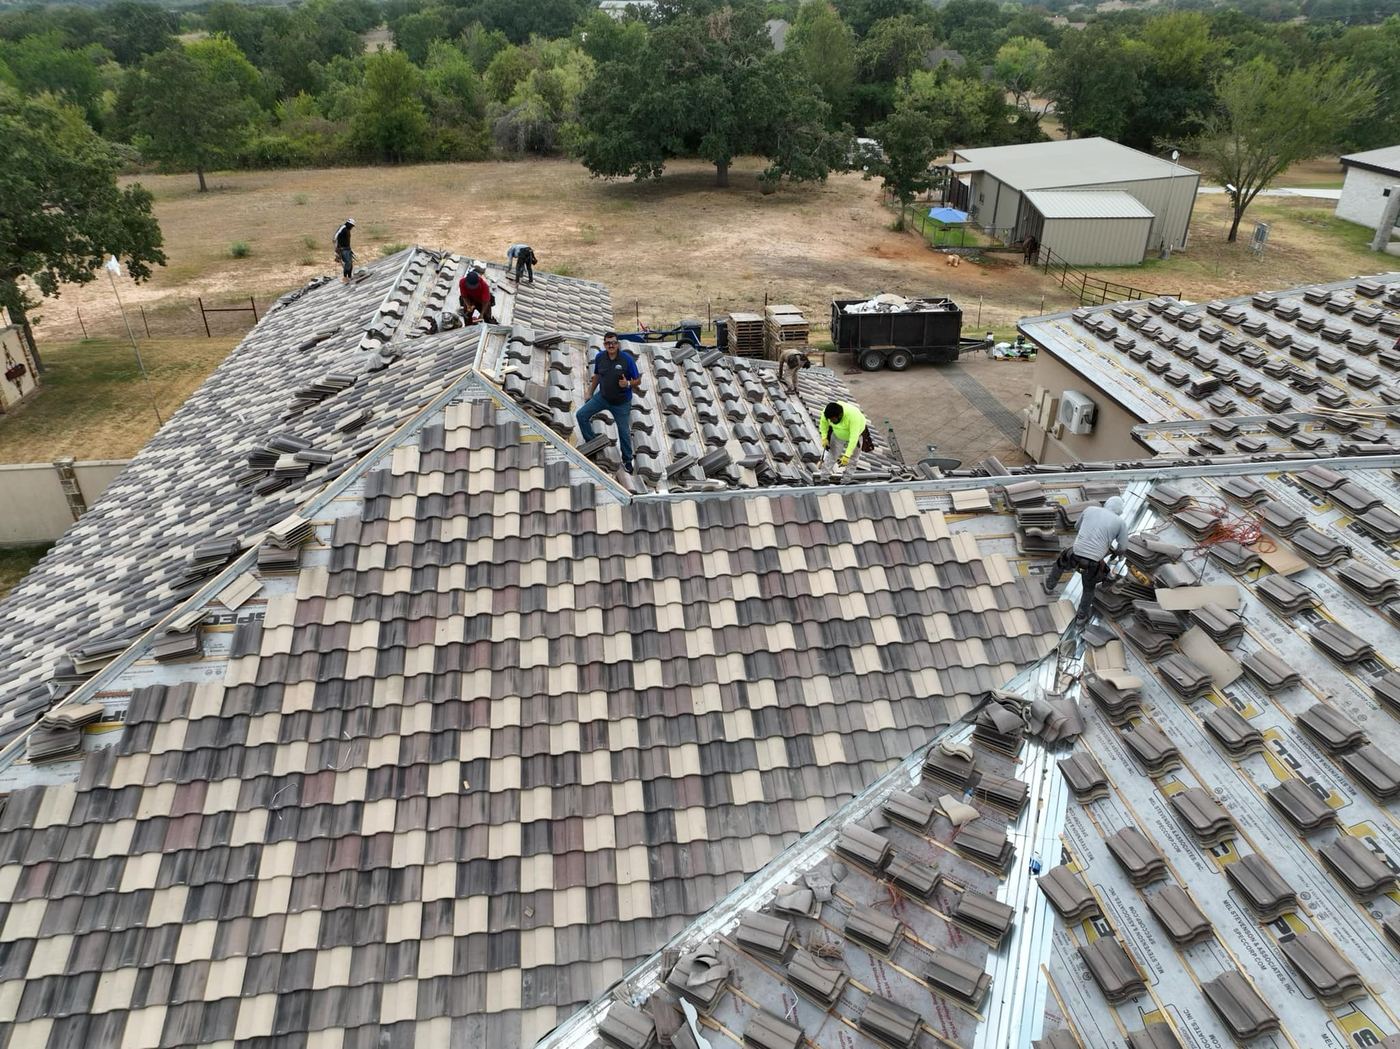
Concrete and clay tile repair and replacement, including broken-tile and underlayment work.
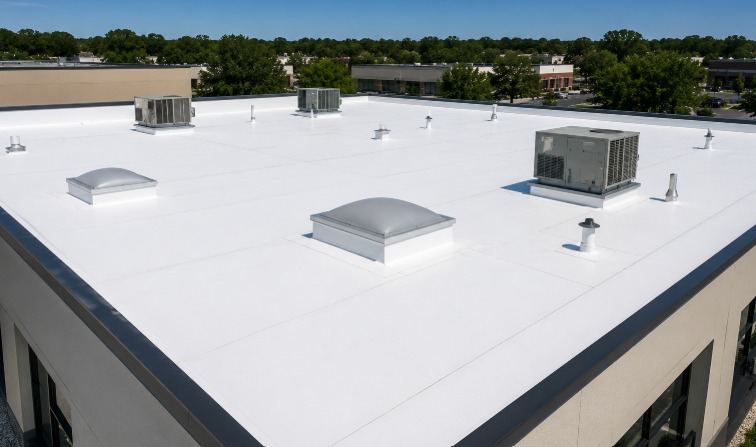
TPO, modified bitumen, and coating systems for low-slope commercial and multifamily buildings.
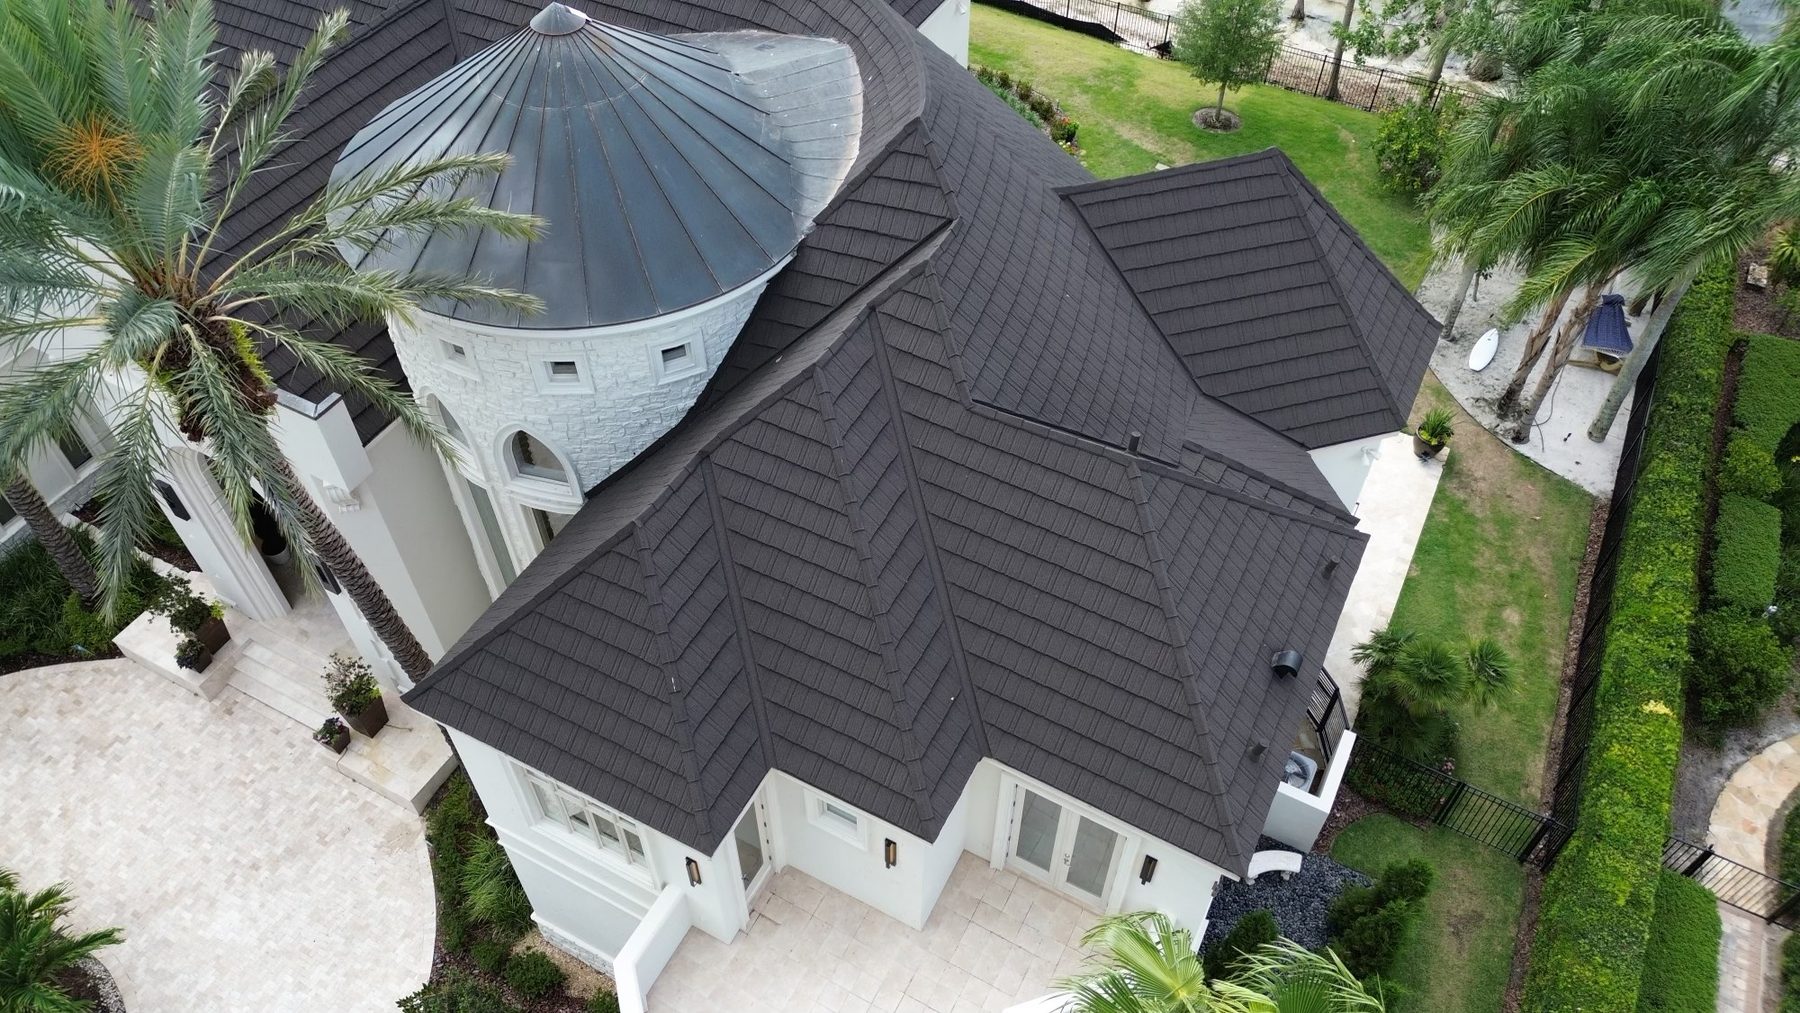
Slate, synthetic slate, cedar shake, and copper detail work on homes that need it done right.
Leaks, flashing, boots, valleys, and wind-lifted shingles — found and fixed properly.
Roof coating systems that extend the life of a low-slope roof without a full tear-off.
The water has to go somewhere. We replace the drainage along with the roof so it works as one system.
We’re not locked to one manufacturer. You pick the shingle you want and we install it to that manufacturer’s specification.

A free report costs you nothing and takes twenty seconds. Worst case, you find out your roof is fine and you stop thinking about it.
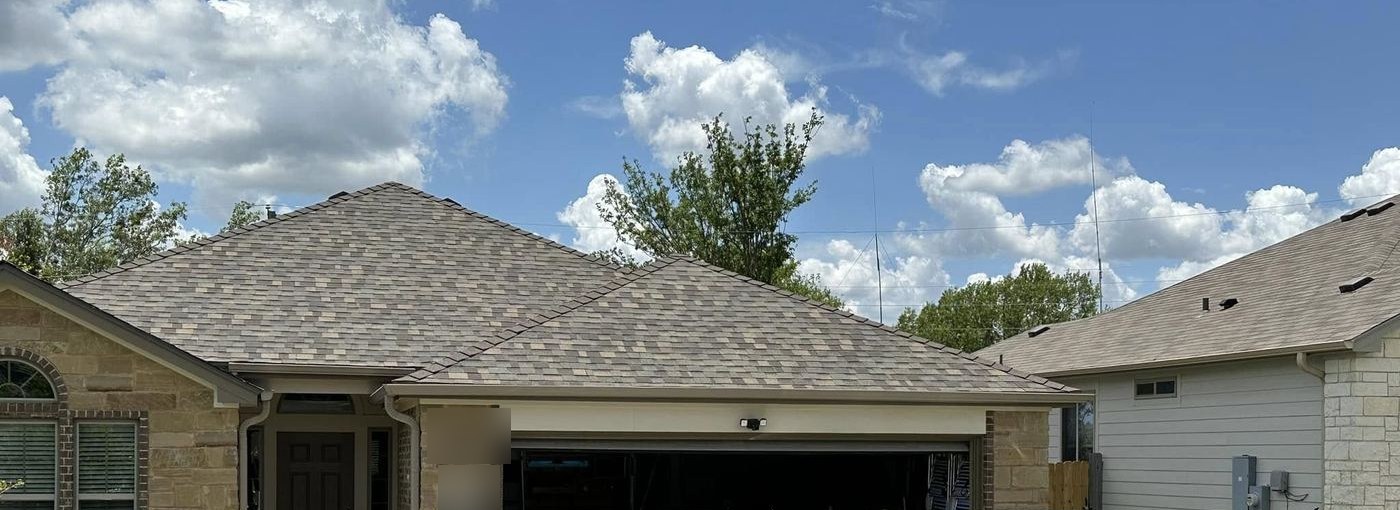
Every photo here is a RezComm job. Tap any one to see it full size.
Choose a day and a window that works. We’ll confirm by phone. About 30 minutes on site, and you’ll need to be home — but you don’t have to go anywhere near the roof.
No mystery and no sales gate. Open a real report and see the level of detail before you ever give us your address.
Sample reports are from completed RezComm jobs with the homeowner’s name, address, and claim number removed.
Every inspection we do is flown and scanned — not eyeballed from a ladder. Pick one below.
If your city isn’t on the list, call us anyway — we cover more ground than we can fit here.
The things homeowners actually ask before they call anyone.
If a storm — hail or wind — caused the damage and it is documented properly, most Texas homeowners policies cover roof replacement, minus your deductible. What they generally do not cover is age-related wear. Documentation before the adjuster arrives is what decides which bucket your roof lands in. Read the full answer.
Usually you cannot tell from the ground, and often not even from a ladder. Look for granule loss, dented gutters and vents, and soft bruising. The reliable way is a free verified storm history report for your address plus a free ScanShield AI drone scan — no visit required for the report. Read the full answer.
Yes. The storm history report and the ScanShield AI drone scan are both free with no obligation, residential or commercial, anywhere in Dallas–Fort Worth. Nobody comes to your address for the storm report at all.
Typically three to eight weeks end to end: filing, adjuster inspection, carrier decision, then scheduling and the build. The stage most likely to stretch is the adjuster inspection after a big storm. Read the full answer.
No, and neither can anyone else. Texas law requires a person insured under a property policy to pay the deductible that applies to their claim. What we do include on qualifying insurance-funded replacements is a free upgrade to impact-resistant shingles at no additional cost — that is a better roof, not a discount on your deductible.
Asphalt shingle, concrete and clay tile, metal, slate and synthetic slate, and commercial flat systems including TPO, PVC, and EPDM. The inspection method changes with the material, because hail damage on tile looks nothing like hail damage on shingle. See all roof types.
Find out whether your roof was hit before your claim window closes.
Real reviews from Google and Thumbtack. Click any one to read it at the source.